

EasyBudget - Budget planning
4.0

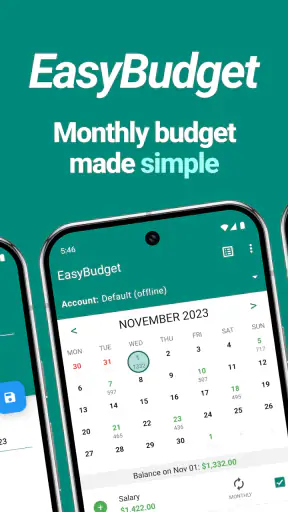
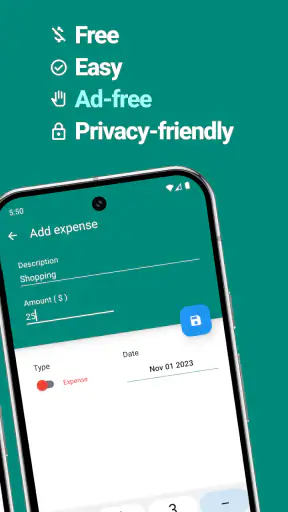
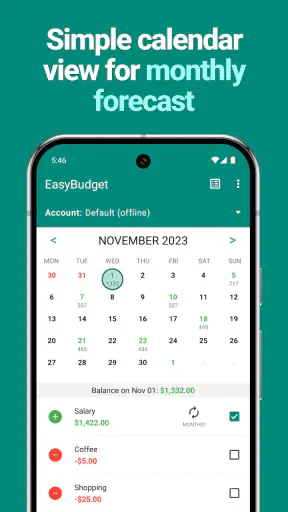
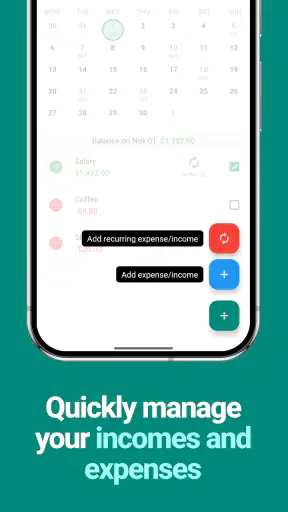
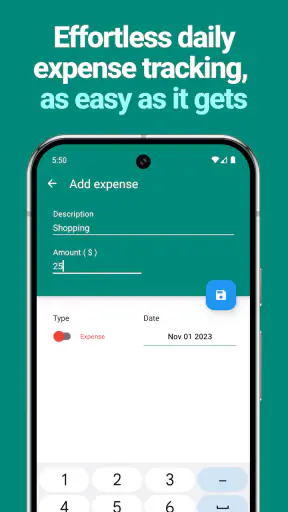
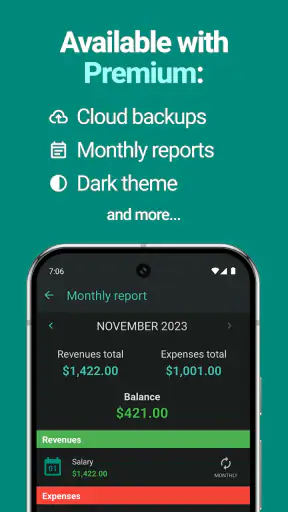
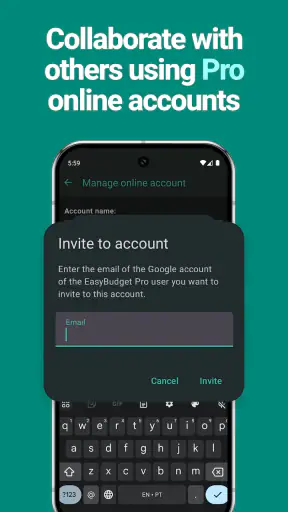
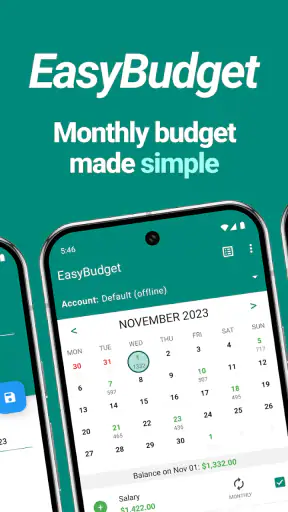
I spent time with EasyBudget as a straightforward finance app for planning monthly spending, and my first impression was that it understands a common problem: many people do not need a complicated accounting system, but they do need a clear place to decide where their money should go. Its focus is narrow, which is helpful when you want a simple budgeting routine rather than a full financial dashboard.
The app is developed by Wallet Passes Alliance and is available for free, with optional in-app purchases ranging from $0.99 to $99.99 per item. It is rated for Everyone, so its presentation is approachable rather than aimed at financial professionals. With a 4.0 average from around 21 thousand ratings and over 500 thousand installs, it has attracted a meaningful audience without feeling like an obscure experiment.
How EasyBudget feels in everyday use
EasyBudget is best understood as a lightweight monthly planning tool. I would open it at the start of a pay period, decide how much I could safely spend, and use the budget as a reference before making ordinary purchases. That workflow is much less intimidating than opening a traditional finance package filled with charts, account connections, investment sections, and terminology I may not need.
The most useful mindset is to treat the app as a planning companion, not as a replacement for a bank account. It can help me think ahead, but it does not make a spending decision for me. If I enter a generous amount for entertainment and then spend it quickly, the app cannot correct that choice. Its value comes from making the limit visible early enough for me to react.
That distinction matters because budgeting apps often fail when they try to do everything. EasyBudget’s appeal is the opposite: I can approach it with one practical question—how much room do I have this month? For someone who has never maintained a budget, that simplicity can make the habit easier to start.
Speed expectations and the first setup
My expectation for an app like this is quick access rather than elaborate processing. Monthly budgeting normally involves small entries and short decisions, so I would not expect the kind of waiting associated with media-heavy apps or large games. EasyBudget’s purpose also suggests a low-friction routine: open it, review the plan, and move on with the day.
The first setup deserves more patience than later check-ins. A useful budget depends on realistic categories and amounts, so rushing through the initial plan can produce a neat-looking but misleading result. I recommend starting with obligations that are difficult to change, then adding flexible areas such as food, transport, and leisure. This makes the remaining amount more meaningful than simply dividing money into arbitrary sections.
A practical trick is to create the budget shortly after receiving income, not when the month is already half over. That gives the app a chance to guide choices before the money disappears into small, easy-to-forget purchases. I also find it useful to leave a modest buffer rather than assigning every unit of currency to a category. A plan with no breathing room can look precise while being fragile.
Because the app is designed for budgeting rather than financial analysis, I would judge its speed by how quickly it lets me answer ordinary questions. Can I check my remaining room before ordering dinner? Can I update a category after an unexpected expense? Can I understand the current position without studying a complicated screen? Those are more important here than advanced visual effects or elaborate reports.
What happens during heavy-use moments
“Heavy use” in EasyBudget is not the same as heavy use in a game. The demanding moments are likely to be periods when I enter several expenses close together, revise a plan after a bill arrives, or review the budget repeatedly during a busy month. These are the situations where a simple tool earns its place, because financial decisions often happen in short gaps between other tasks.
I would use a quick review before a grocery trip, after a weekend out, and again before a recurring payment is due. That rhythm is more useful than waiting until the end of the month and discovering that the budget was unrealistic from the beginning. The app works best when it becomes a small checkpoint rather than a once-a-month confession.
One non-obvious advantage of this approach is that it can expose the difference between planned spending and emotional spending. If I notice that one flexible category repeatedly needs adjustment, the problem may not be the app or the budget itself. The category may be too broad, or I may be underestimating a regular habit. Splitting a vague “miscellaneous” amount into clearer groups can reveal where the plan is actually leaking.
There is also a trade-off. A simpler budget can be faster to maintain, but it may not satisfy someone who wants detailed transaction analysis. If I need automatic classification, complex household accounting, investment tracking, or a deep history of financial trends, I would look toward a more specialized alternative. EasyBudget makes more sense when manual planning is acceptable and clarity matters more than automation.
Reliability, consistency, and recovering from mistakes
Reliability in a finance app is not only about whether it opens. It is also about whether I can trust my own routine. A budget becomes useful when I enter information consistently and interpret it the same way each time. EasyBudget’s focused purpose supports that habit, but it cannot remove the need for careful input.
I would avoid making a new category every time an unusual purchase appears. That creates a cluttered plan and makes future months harder to compare. Instead, I would decide whether the expense belongs in an existing flexible category or deserves its own recurring place. This is a small organizational choice, but it has a large effect on how readable the budget remains.
Recovery is another important part of the experience. If I make an unrealistic estimate, the sensible response is to revise the plan rather than abandon budgeting altogether. A failed month should teach me something: perhaps a bill was forgotten, a category was too narrow, or the available amount was calculated before essential commitments were removed. The app is more useful when I treat changes as feedback instead of as evidence that budgeting does not work.
I would also keep my own basic reference for important figures, especially during the first few weeks. That is not because EasyBudget is unsuitable for budgeting; it is because financial habits benefit from a backup perspective. A short note about income, fixed commitments, and the intended buffer can make it easier to rebuild a plan if I accidentally change something or decide to reorganize my categories.
For a couple or family, reliability depends on agreement as much as software. If only one person updates the plan while another spends from the same pool, the numbers can quickly become stale. EasyBudget may suit a household that has already agreed on a simple method, but a shared-finance solution with stronger collaboration tools may be the better choice when several people need simultaneous visibility.
Device constraints and practical expectations
The current version is 4.1.0, and the app supports devices running Android 7.0 or later. That gives it a relatively broad reach for people using older Android hardware, which is useful if replacing a phone is not part of the budget. The Everyone content rating also makes it suitable for a wide range of users who want an uncomplicated money-planning tool.
On an older device, I would still keep expectations sensible. Budgeting does not require the same resources as video editing or modern 3D games, so the app’s basic purpose should fit comfortably into a modest phone setup. However, the overall experience can be affected by the device’s age, available storage, background activity, and general system condition. A finance app cannot make an aging phone responsive in every situation.
Resource demands are best judged by the job EasyBudget performs. It is not a media library, social feed, or graphics-intensive game, so I would choose it for a phone where I want a focused utility rather than another demanding application. The benefit is not only potential responsiveness; it is also mental economy. Opening a small budgeting tool feels more appropriate for a quick money check than launching a large, feature-heavy financial suite.
Older Android users should pay attention to the minimum operating-system requirement before trying to install it. If the phone is below Android 7.0, this particular app is not the right route, and upgrading the device or choosing a compatible budgeting alternative would be more practical. For supported phones, keeping the operating system reasonably maintained is still a good idea when handling personal financial information.
iPhone users should also check the relevant platform availability before planning around it, because the confirmed compatibility details here describe Android support. That does not make the app less useful for Android owners; it simply means platform choice should be part of the decision. Someone who moves between Android and iOS may prefer a budgeting service designed around cross-device access.
A realistic monthly scenario
Imagine I receive my income, set aside rent and other fixed commitments, and then want to control the flexible remainder. I could use EasyBudget to give groceries, transport, personal spending, and leisure their own limits. Before an unplanned purchase, I would check the relevant category rather than relying on a vague feeling that there should still be enough money left.
Midway through the month, an urgent repair might force me to change the plan. Instead of pretending nothing happened, I would reduce a less essential category and keep the budget honest. This is where a simple app can be more useful than a spreadsheet that I created once and rarely reopen. The value is in making the adjustment part of the normal routine.
At the end of the month, I would look for patterns rather than judging myself by a single total. If groceries consistently exceed the original estimate while entertainment remains untouched, next month’s plan should reflect that reality. If several tiny purchases are responsible, I might create a clearer rule for them. This turns EasyBudget from a passive record into a tool for making better estimates.
Who should choose it, and who should skip it
I would recommend EasyBudget to a person who wants a clear monthly structure, prefers a focused interface, and is willing to enter or review information manually. It is especially suitable for beginners who find conventional financial software overwhelming. The free entry point also makes it easy to try the budgeting method without committing to a paid financial platform.
It can also suit someone with an older supported Android phone who wants a practical utility rather than a resource-heavy application. The broad Android compatibility and straightforward finance focus make it a reasonable option for basic planning, provided the user is comfortable maintaining the budget personally.
I would skip it if my main requirement were automatic bank synchronization, sophisticated reporting, investment monitoring, or detailed shared access for a household. Those needs call for a broader financial service, even if that service takes longer to learn. I would also avoid relying on it as the only record for complicated business finances, where tax categories, invoices, and multiple accounts require more specialized tools.
The optional purchases deserve a thoughtful approach too. Since the app is free but offers items from $0.99 to $99.99, I would first use the basic experience and decide whether any paid addition genuinely improves my routine. A budgeting purchase should solve a specific problem, not become another unplanned expense. That is a particularly important test for an app whose purpose is financial control.
How it compares with spreadsheets and larger finance apps
A spreadsheet offers almost unlimited flexibility, but that flexibility can become a burden. I can design any layout I want, yet I also have to maintain formulas, formatting, and structure. EasyBudget is the more approachable choice when I want the budget itself to be ready for regular use rather than spending time building the system.
A bank’s own tools may provide a closer view of transactions, but they are often tied to one institution. EasyBudget is more suitable for a personal plan that begins with intentions and limits, not only with transactions already processed. That makes it useful before spending happens, which is exactly when a budget can influence a decision.
Full finance apps usually win on breadth. They may be better for people who want accounts, investments, recurring transactions, detailed reports, and long-term financial analysis in one place. EasyBudget wins when those extras would distract me. The trade-off is clear: I get a simpler monthly planning experience, but I should not expect it to replace an entire financial management system.
My performance verdict
EasyBudget succeeds because its job is easy to understand. I can use it as a compact checkpoint for monthly spending, and its Android 7.0 minimum requirement keeps it accessible to many older devices. I would expect it to be more comfortable on a modest phone than a feature-packed finance suite, although the quality of the experience will still depend on the device and on how consistently I maintain the plan.
Its biggest strength is not a flashy feature; it is the reduction of friction between deciding to budget and actually checking the plan. Its biggest limitation is the same simplicity. People who want automation, deep analysis, or complex collaboration may quickly outgrow it.
After using it, my recommendation is straightforward: try EasyBudget if you want a free, focused monthly budgeting habit and are happy to stay involved with your own entries. Start with realistic fixed commitments, preserve a buffer, review the plan during the month, and revise categories when your real behavior proves the estimate wrong. For basic monthly control, that combination of focus and low overhead is the app’s strongest reason to stay installed.
Wallet Passes Alliance has positioned this finance app for ordinary budgeting rather than expert accounting, and I think that is the right audience. It will not solve every money-management problem, but for someone who needs a simple place to plan, check, and adjust monthly spending, EasyBudget is a sensible option to consider.
4.0
2.55K Reviews
Pros
- Simple interface makes it easy to record income and expenses quickly.
- Custom categories help organize spending according to personal habits.
- Budget limits provide a clear view of remaining funds.
- Useful summaries can reveal spending patterns over time.
- Suitable for users who want straightforward personal finance tracking.
Cons
- May lack advanced investment and debt-management features.
- Manual transaction entry can become time-consuming for active accounts.
- Limited automation may require frequent updates from the user.
- Some features may be restricted or supported by in-app purchases.
- Budget accuracy depends entirely on consistent and careful data entry.


